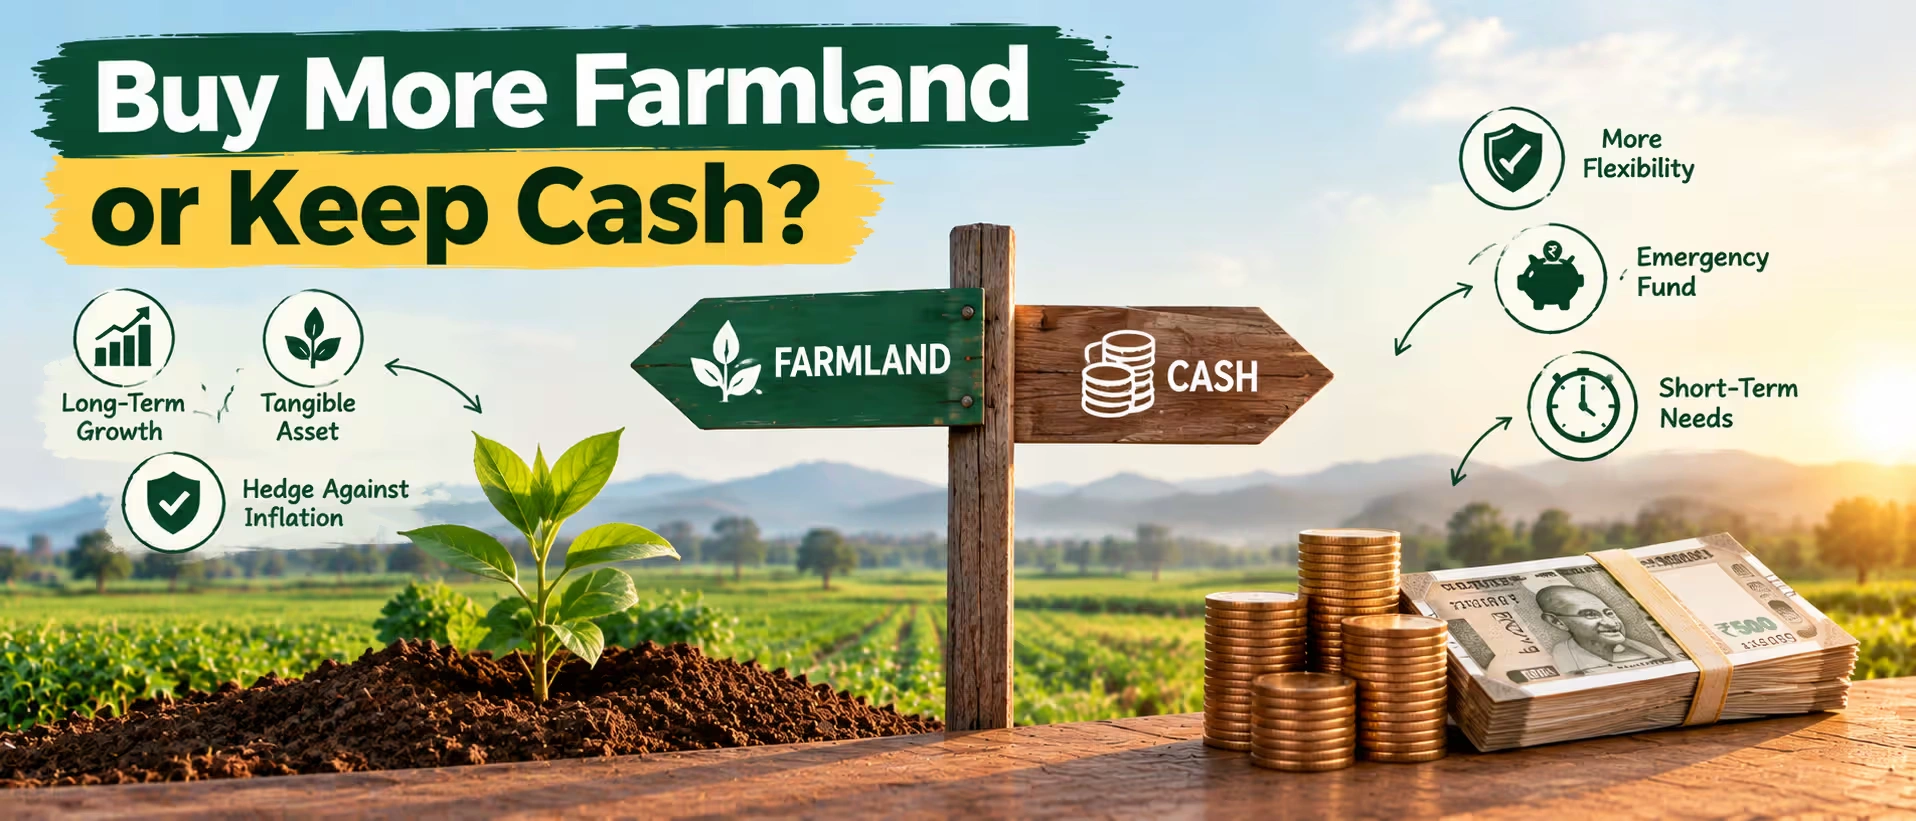
If most of your money is already invested in land, buying additional land will make you less flexible rather than more secure. The liquidity offered by fixed deposits, debt funds, and other listed instruments will give you returns in a different manner, but at least they give you access to your money in just a few days' time. It all boils down to your requirement for the extra money and how much of your net worth is tied up in the farm. This is the quick answer. The rest of this article is devoted to explaining the pros and cons in simpler terms, even with an example.
Start With How Much of Your Wealth Is Already in Land
A farmer with 10 acres, a house, and limited savings may already have most of their wealth tied up in land. The same applies to an urban professional who inherits family property and has little cash left to invest in farm land for sale or other assets.
Before deciding where new money goes, add up what you hold: land at a realistic market value, house, gold, bank deposits, investments, and any loans. If land is well over half of the total, a further purchase raises the concentration. If land is a small part, say you live in a city and own one inherited plot, buying more may be a perfectly reasonable step.
What Each Option Does Well?
| Point | More agricultural land | Liquid investments |
| Regular income | Low, often under 2 to 3 percent of the land value a year from farming or lease | Interest or dividends, usually higher than farm income on the same amount |
| Growth | Depends on location; can be strong near new roads and towns, flat elsewhere | Depends on the instrument; market-linked ones go up and down |
| Access to your money | Slow; selling can take months | Fast; days for most options |
| Cost to enter and exit | Stamp duty, registration, legal checks, broker fees | Small charges, exit loads on some funds |
| Effort | High; boundary, caretaker, paperwork, disputes | Low |
| Main risk | Title problems, no buyer when you need one, local price stagnation | Market falls, low interest after tax, inflation |
| Protection against inflation | Often decent over long periods, but not guaranteed | Varies; fixed deposits can lag inflation |
Neither column wins everywhere. Land is good at holding value over many years and at being something you can use. Liquid assets are good at paying you and at being there when you need them.
A Worked Example With Assumed Numbers
The numbers below are for illustration only. They are not forecasts or current market rates, so swap in your own. Say you have about ₹32 lakh available.
| Item | Buy one more acre | Put it in liquid instruments |
| Money used | ₹30,00,000 price plus 6 percent costs (₹1,80,000) = ₹31,80,000 | ₹31,80,000 |
| Assumed yearly income | ₹60,000 from farming or lease | 6.5 percent a year = about ₹2,06,700 (before tax) |
| Assumed yearly price rise | 5 percent of ₹30 lakh = ₹1,50,000 (not received until you sell) | Included in the 6.5 percent above |
| Total yearly gain on paper | ₹2,10,000 (about 6.6 percent of ₹31.8 lakh) | About ₹2,06,700 |
| Cash in hand each year | ₹60,000 | About ₹2,06,700 |
On these assumptions, the two come out close on paper, but in different forms. The land gives you a small yearly income and a larger gain that you only see when you sell. The liquid option gives you all of it as money you can use.
Now change one number. If the land rises only 2 percent a year, the land's total gain falls to about ₹1,20,000, which is under 4 percent of the cost, and the liquid option clearly wins. If the land is in a growing area and rises 8 percent a year, land comes out ahead. This is the whole decision: it rests almost entirely on how much you believe the land price will move, and the cost of buying and selling land makes small gains disappear. Selling costs and the time to find a buyer are also left off the table.
Questions That Matter More Than Returns
Think about your situation, not only the percentages.
- Will you need this money within three to five years, for a wedding, a child's education, a loan repayment, or a medical emergency?
- Does the new land join your existing holding, so that it saves you effort and lifts your farm income directly? Adjoining land is a different thing from a plot 80 km away.
- Do you have the time and the people to manage another property?
- Do you already have an emergency fund of several months of expenses in an easy-to-reach place?
If you answered yes to the first question or no to the last, liquid investments should probably come first. Buying more land can wait, and good opportunities will arise again. If you later consider selling property online to free up funds, you can reinvest the proceeds when your financial needs and priorities are clearer.
When Buying More Land Is Reasonable?
Land could be a good choice in a couple of scenarios. One scenario would be where the field next to you is for sale, and it becomes easy to manage the larger holding together through irrigation or access. Another scenario would be where there is a research-backed expectation of appreciation due to a road, an industrial estate, or a market planned in the region. And the final scenario would be one where the cash flow has been sufficient, and the new land comprises only a small proportion of the total.
As usual, the same level of verification should be done. It should include the revenue record, the mutation report, the encumbrance certificate, and compliance with the state law regarding permissible buyers for agricultural land.
When Liquid Investments Are the Better Home?
Liquid assets are the better choice when you may need the money soon, when your land is already most of your wealth, or when you cannot supervise another plot. They also suit someone who wants a regular income, since land rarely gives that. A mix of a bank deposit for near-term needs and a market-linked fund for the longer term is a common approach, though you should pick instruments with a registered adviser or an agent you trust, since each has its own risk and tax treatment.
Don't Forget Tax
Tax treatment can change the comparison. Whether farmland is treated as a capital asset for tax purposes can depend on whether it lies in a rural or an urban area, and gains from selling land may be taxed differently from interest income. Some exemptions apply if proceeds are reinvested in specific ways. The rules have also been revised recently, so ask a chartered accountant to check the current position for your case before you buy or sell land. Interest from deposits is generally taxable at your slab rate, which lowers the real return.
The Middle Path
Most landowners have no need to choose one side or the other. You can invest some amount of money in land and keep the rest in liquid assets. Or you can just wait: keep the money in a liquid asset for a year, monitor the prices in the area, and purchase only when a plot that passes your checks appears.
Should you decide to search, searches for plots for sale near me or farmlands near me will bring up a very long list in most cases, and the asking prices in them will not be equal to the price at which land will actually be sold. Compare each plot with recent registered sales nearby. 2Bigha allows you to browse agriculture land for sale in India and compare their locations, size, and asking price.
Some landowners also take into consideration the opposite strategy. Should part of your holding be located far from your place of residence or remain unused, the sale of land and investing the proceeds in liquid assets will work better than purchasing new plots. Any person who sells his property online needs to have the revenue record, mutation papers, and previous deeds ready since buyers will ask for them.
Disclaimer: This article is for informational purposes only and should not be considered investment, legal, financial, or property advice. Real estate regulations, infrastructure plans, market conditions, and government policies may change over time. Readers are advised to verify information with relevant authorities and consult qualified professionals before making any investment or property-related decisions.